 Course Overview
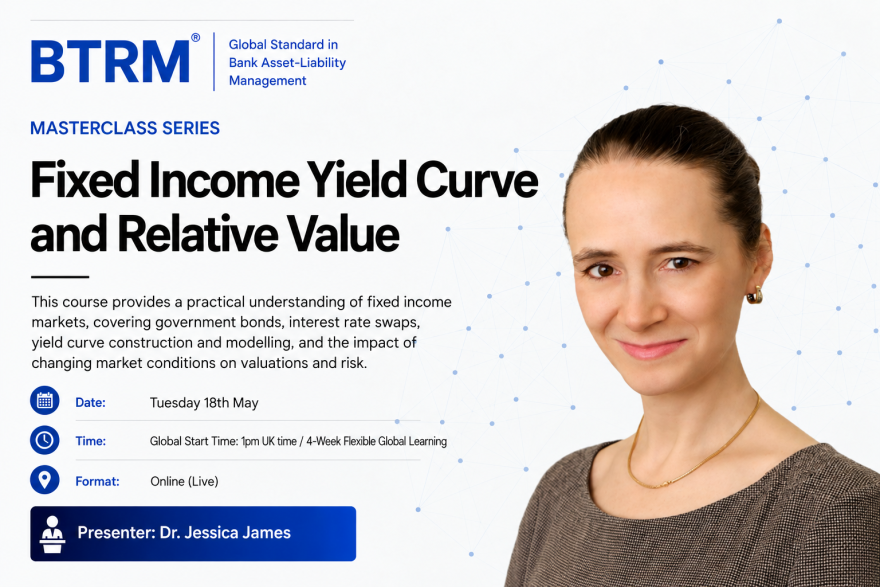
This course provides a practical understanding of fixed income markets, covering government bonds, interest rate swaps, yield curve construction and modelling, and the impact of changing market conditions on valuations and risk. Participants will learn how to identify relative value opportunities, structure yield curve trades, and use repo and bond futures markets to manage positions and exposures.
The course also explores systematic approaches to fixed income trading, including the design, implementation and evaluation of historical backtests. Through practical examples such as carry and roll-down strategies, participants will develop a rigorous, evidence-based framework for evaluating trading opportunities and making informed investment decisions.
Start Date: Tuesday 18th May
Limited Availability: Enrol today
Delivery Mode: Live Online (flexible learning over 4 weeks, 1 lecture per week)
Global Start Time: Accessible for many participants worldwide.
Structured Assessment: Multiple-Choice Test & Certificate
Total Lecture Hours: 20 hours
Instructor: Dr. Jessica James
Empowering Global Talent: Emerging Markets Subsidy
BTRM Alumni and Current Students: 40% Discount (off the standard fee)
A lecture style course with demonstrations and spreadsheet takeaways/homework over 4 days (1 day per week, total teaching 20 hours)
Who is this for?
- Treasury professionals looking to refresh their knowledge and stay ahead of the curve
- Students or banking and finance professionals who have taken or are taking the BTRM qualification, who are interested in the bond markets, how they function and how they may be used for investment purposes
Learning outcomes
- Understanding of government bonds and swaps; construction, valuation and sensitivity to market environments
- Yield curve construction, evolution, history and modelling techniques
- How to construct fixed income trades to take advantage of relative value opportunities on the yield cuve
- A good understanding of the repo and bond futures market, and how bonds, repos and futures relate to each other and can be used to balance positions and manage risk
- Backtesting bond and yield curve strategies; how to set up a backtest, run it and evaluate it, with examples from history like carry and roll. This will enable participants to apply rigour and a scientific approach to their position taking
Weekly Forum:
Q&A weekly lecture forum. Students can submit question on the forum that will be answered live in weeks 2, 3, and 4.
Multiple-Choice Test & Certificate:
The BTRM Advanced Treasury Masterclass Series ends with a Multiple-Choice Test. This test is available for one month after the final lecture week.
Learning Resource:
Students get to keep the training for 12 months post course.
Pricing Structure:
- BTRM 40% Alumni & Students – Please submit an enquiry
- Discounts Available: Super Early Bird 20% & Early Bird 10%
- Emerging Markets Discount – Please submit an enquiry
- Group Discount – If 2 or more people from your institution wish to join the masterclass please contact us.
- VAT exemption – If you are a non UK or EU resident, you are exempt from VAT.
4-Week Flexible Global Learning
The BTRM Advanced Treasury Masterclasses run over four weeks in a live online format offering a highly effective learning experience by balancing depth, flexibility, and Faculty engagement.
With a start time of 1pm UK time enabling students to join live from many locations around the world. The live format encourages real-time interaction with the Faculty instructors and peers, fostering deeper discussions and immediate problem solving. Spacing the sessions weekly also accommodates the busy schedules of banking professionals, ensuring minimal disruption to daily responsibilities while maximising learning retention and practical application. The course ends with a structured assessment multiple-choice test & certificate. Students get to keep the course in their own personal BTRM educational portal for 12 months.